Introduction
Buying D&O insurance is different from buying a standard business policy. In particular, there is no fixed product off the shelf. Instead, the insurer needs to understand the company, its board, and its risks before it can quote. Likewise, the buyer needs to understand the policy wording before accepting it.
This guide walks through the Buying Process of D&O Insurance from start to finish. Specifically, it covers what information you need, how to obtain and compare quotes, what to check in the wording, how payment and issuance work, and what to do after purchase. It also answers a common question: can directors buy a D&O policy for themselves?
What Is D&O Insurance?
Directors and Officers (D&O) Liability Insurance protects directors, officers and, depending on the policy, the company itself against claims alleging wrongful acts in managing the business. Generally, it pays defence costs and, where covered, settlements or awards, subject to the policy terms, limits and exclusions.
A D&O policy generally has three insuring clauses:
- Side A – pays for insured individuals when the company does not indemnify them
- Side B – reimburses the company when it indemnifies its directors and officers
- Side C – protects the company itself for certain claims, where included
For a full explanation, see SecureNow’s guide to Side A, B and C covers in a D&O policy.
Why Should a Company Consider D&O Insurance?
Directors and officers can face claims personally for decisions made on the company’s behalf. Moreover, claims may come from shareholders, lenders, regulators, employees, creditors, or other third parties. Furthermore, defence costs alone can be high, even when the allegation fails.
In India, directors have statutory duties under Section 166 of the Companies Act, 2013. In addition, for the largest listed companies, SEBI’s Listing Regulations require D&O insurance for independent directors. However, for most private companies, buying D&O is a governance and risk decision rather than a legal requirement. Investors, lenders, or prospective board members may still expect it.
The right level of cover differs from company to company. For example, a small private company and a listed group face very different exposures.
Who Can Be Covered Under a D&O Policy?
The company is usually the policyholder, and directors and officers are the insured persons. However, the exact definition of “insured person” depends on the policy wording. For instance, it may include:
- Directors, including executive, non-executive, independent, and nominee directors
- Officers, such as the company secretary or chief financial officer
- Senior managers or employees acting in a managerial capacity, depending on the policy
- Former directors and officers, for acts during their tenure
- Estates, heirs or legal representatives of insured persons, where the policy extends to them
- Directors serving on outside boards at the company’s request, where outside directorship cover applies
See who is covered under a D&O policy for more detail.
Step-by-Step Buying Process for D&O Insurance
The steps below describe a typical buying process for D&O Insurance. However, actual steps and documents vary by insurer, intermediary and policy.
Step 1: Assess Your D&O Insurance Requirement
Start by understanding why the company needs cover and how much exposure it faces. In particular, consider:
- Board structure – number of directors, as well as independent and nominee directors
- Officers – especially key managerial personnel with decision-making authority
- Business activities – especially products, services and customers
- Regulatory exposure – especially sectors with active regulators or licensing
- Investor and shareholder expectations – particularly those in shareholder agreements
- Employment decisions – such as hiring, termination and workplace conduct
- Financial responsibilities – such as borrowings, guarantees and reporting
- Litigation exposure – such as past disputes and likely claimants
- Company structure – particularly subsidiaries and overseas entities
- Status – private, public or listed
Consequently, the answers shape everything that follows: the limit, the extensions and the insurers likely to be interested.
Step 2: Identify the People Who Need Coverage
List the people the policy must protect. First, include current directors and officers. Then check whether the wording should also cover:
- Former directors and officers, for acts during their tenure
- Senior managers or employees with management roles
- Directors serving on outside boards
- Directors of subsidiaries
Ask how each quotation defines “insured person”. This matters because definitions differ, and a narrow definition can leave some people outside the cover.
Step 3: Gather Information for the Quote
Insurers need information to underwrite the risk. Requests vary by insurer and policy, but commonly include:
| Information Area | Examples of What May Be Requested |
|---|---|
| Company details | Name, registration, date of incorporation |
| Nature of business | Activities, products, customers |
| Financials | Revenue or turnover, assets, recent financial statements where required |
| Board and management | Number of directors, key officers, governance structure |
| Ownership | Shareholding pattern, investors, promoter holdings |
| Operations | Locations, subsidiaries, overseas activity |
| Listing status | Whether listed, and on which exchange |
| Claims history | Past claims, pending litigation, known circumstances |
| Regulatory matters | Notices, investigations or penalties |
| Existing insurance | Current D&O policy, limit, retention, expiry |
| Cover sought | Desired limit, retention and extensions |
Give accurate and complete information. Otherwise, gaps or errors can delay quotes. More seriously, they can affect cover if a claim arises later.
Step 4: Decide the Required Coverage and Policy Limit
Before requesting quotes, decide what you are trying to buy:
- Policy limit – the maximum the insurer will pay
- Aggregate limit – generally the total for all claims in the policy period
- Retention or deductible – the amount the company bears before the policy pays, often applying to Side B and C
- Side A, B and C – which insuring clauses you need
- Defence costs – how they are paid and also whether they reduce the limit
- Extensions – such as regulatory investigation cover, entity EPLI or run-off, where available
- Sublimits – lower limits within the policy for particular covers, such as certain extensions
- Excess or layered cover – for larger programmes, additional limits placed with other insurers
Do not choose a limit only on price. Instead, base it on the company’s exposure, and review it as the business grows. SecureNow’s article on what drives the cost of a D&O policy explains how these choices affect premium.
Step 5: Obtain D&O Insurance Quotes
Generally, quotations can be obtained through:
- Insurance brokers or intermediaries – who approach several insurers and then help compare terms
- Insurers directly – where they deal directly with commercial clients
- Online platforms – which collect company details and then return indicative quotations, where available
Whichever route you choose, give the same information to every insurer. Otherwise, inconsistent information produces quotes that cannot be compared.
Video: How to Buy a D&O Policy
In this short SecureNow video, our team shows how to request and compare D&O quotations online.
Step 6: Compare Quotes on a Like-for-Like Basis
A lower premium may simply reflect a lower limit, a higher retention, or narrower cover. Therefore, use a worksheet to line up the quotations:
| Feature | Quote A | Quote B | What to Compare |
|---|---|---|---|
| Policy limit | Same limit? Any per-claim limit? | ||
| Retention | Amount and which clauses it applies to | ||
| Side A | Included? Any additional Side A limit? | ||
| Side B | Retention and conditions | ||
| Side C | Included? Scope of entity cover | ||
| Defence costs | Advanced or reimbursed; inside or outside limit | ||
| Key exclusions | Exclusions in one quote but not another | ||
| Extensions | Which are included; sublimits | ||
| Territorial/jurisdiction scope | India only, worldwide, or excluding certain countries | ||
| Premium | Base premium | ||
| Taxes/charges | GST and any other charges | ||
| Insurer/policy wording | Standard wording and endorsements |
For more on choosing between insurers, see criteria for selecting a D&O insurance company.
Step 7: Review the Policy Wording and Exclusions
The quotation summarises the cover; the wording defines it. Before deciding, review:
- Insuring clauses – what the insurer promises to pay
- Definitions – “claim”, “wrongful act”, “insured person”, “loss”
- Exclusions – what is not covered; also see exclusions in a D&O liability policy
- Conditions – your duties, such as cooperation and consent
- Retention – how it applies to each clause, especially Side B and C
- Defence-cost provisions – advancement, consent and choice of counsel
- Claims-made structure – also see D&O liability insurance – a claims-made policy
- Reporting requirements – how and when to notify claims
- Prior or pending litigation – how existing matters are treated
- Retroactive date – also see the importance of the retroactive date
- Territorial and jurisdiction terms
- Extensions, limits and sublimits
Wordings differ between insurers. Therefore, avoid assuming that two policies with similar names provide the same cover.
Step 8: Complete the Proposal and Underwriting Process
Once you choose a quotation, the insurer will usually require a signed proposal form. Following this, the underwriting stage may involve:
- Completing and signing the proposal or application
- Answering underwriting questions
- Providing additional documents, whenever the insurer asks for them
- Clarifying information previously supplied
- The insurer’s review of the risk
- Revisions to the quotation, whenever the insurer’s view changes
Disclose all relevant information, including known circumstances that could lead to a claim. Otherwise, non-disclosure or misstatement can give the insurer grounds to dispute cover. In practice, known circumstances are often excluded from a new policy anyway. Nevertheless, disclosing them keeps the position clear for both sides.
Step 9: Select the Policy
Choose the policy that best fits the company’s needs. In particular, weigh:
- Coverage and insuring clauses
- Limit and retention
- Exclusions and extensions
- Defence-cost treatment
- Policy wording quality
- Premium, including taxes
- Insurer suitability and D&O experience
- Claims handling and service
- The company’s own requirements
The cheapest option is not automatically right, and neither is the most expensive. Instead, the right choice is the one that fits the company’s exposure.
Step 10: Pay the Premium and Confirm Policy Issuance
- The premium is usually paid before cover starts. Under Section 64VB of the Insurance Act, 1938, an insurer generally cannot assume risk until the premium is received, or guaranteed or deposited as the law allows.
- GST applies to D&O premiums. However, the September 2025 exemption covers individual life and health insurance only.
- Allow time for payment to clear before the intended start date.
- Also confirm the start date and time shown on the policy.
- Afterwards, the insurer issues the policy schedule and wording, and any endorsements.
- Finally, check that the documents match what you agreed.
Generally, payment methods and timelines depend on the insurer.
Step 11: Review the Policy After Purchase
Buying the policy is not the end of the process. Therefore, on receipt, review:
- The policy schedule – names, period, limit, retention and premium
- The full wording and endorsements
- Insured persons and entities
- Exclusions and extensions
- Insurer and broker contact details
- The claims notification process
- The renewal date
Keep the policy where the board and legal team can find it. Also brief directors on what the cover does and does not include.
Similarly, business changes can affect cover. For example, acquisitions, new subsidiaries, overseas expansion, a listing or a change of control may need to be notified during the policy period or reviewed at renewal, depending on the policy terms. In addition, some add-ons can be requested mid-term – see adding add-on cover after buying D&O insurance. Finally, renewals are re-underwritten each year; see renewing a D&O policy.
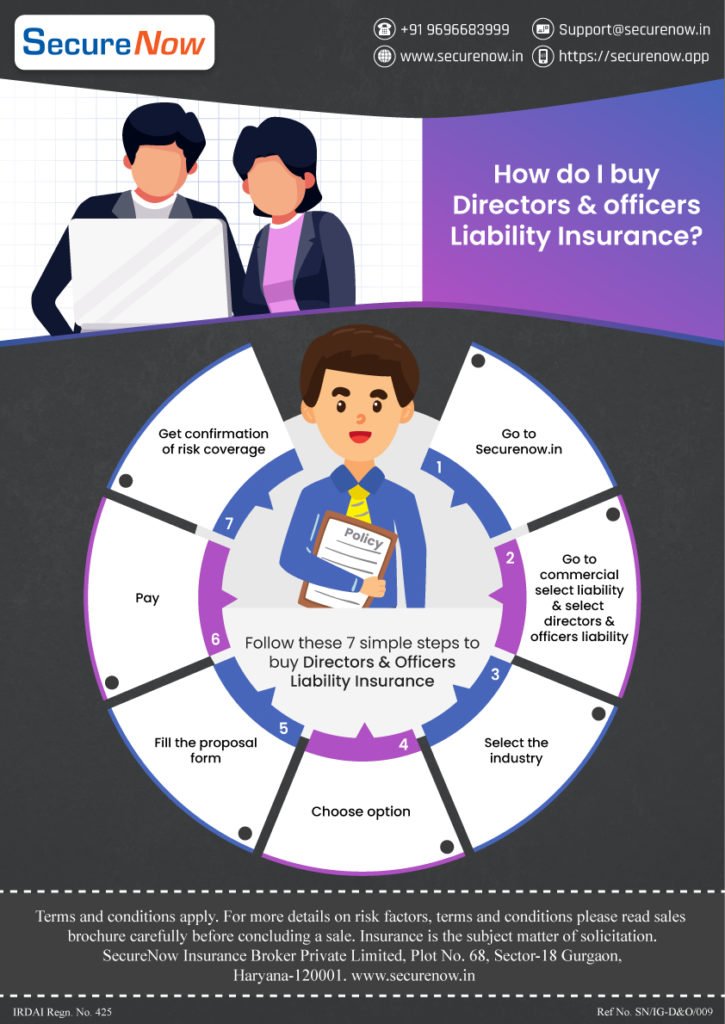
Infographic: Buying Process of D&O Insurance
This SecureNow infographic summarises the main stages of buying a D&O policy. You can also use it as a quick reference alongside the steps above.
How to Buy a D&O Insurance Policy Online from SecureNow
If you are wondering how to buy a D&O insurance policy online from SecureNow, the journey follows the same principles as any D&O purchase. The main difference, however, is that the first steps happen online.
At the time of writing, SecureNow’s D&O quote form on its Directors & Officers Liability Insurance page works in three stages:
- Contact details. First, enter the company name, city, mobile number, and email address.
- Industry classification. Then select the company’s industry.
- Finally, view quotations from insurers and choose the coverage you want to compare.
After that, a typical purchase continues as follows:
- Compare coverage and terms – limits, retention, exclusions, and extensions.
- Provide underwriting information – insurers may need more details before confirming terms.
- Select the policy that suits the company’s needs.
- Complete the proposal and documentation required by the insurer.
- Then pay the premium.
- Finally, receive the policy documents and review them.
The exact steps, information requested, and completion process depend on the insurer and the company’s risk profile, and the online form may change. SecureNow’s team can also be contacted directly for help with requirements or comparisons.
Buying online is a convenient way to start. However, it does not replace reading the policy wording before you commit.
Can Directors Buy D&O Policy for Themselves?
In most cases, the company buys the D&O policy and its directors and officers are insured persons under it. As a result, directors rarely need to buy a separate policy. In addition, whether an individual can arrange personal cover depends on what insurers in the market offer.
Policyholder vs insured person
These two roles are often confused:
- Policyholder – the entity that buys the policy and pays the premium. For standard D&O, this is generally the company.
- Insured person – anyone the policy protects. Directors and officers are insured persons, even though they did not buy the policy themselves.
In short, this structure is why a director is usually protected without a personal contract with the insurer.
Why companies usually buy D&O
- One policy covers the whole board. This matters because claims often name several directors, and a single policy responds to all insured persons, subject to its terms.
- The policy can also cover the company. Side B reimburses the company for indemnifying directors, and Side C may cover the company itself.
- In addition, the company holds the underwriting information insurers need, such as financials, governance, and claims history.
- The law allows the company to pay. Under Section 197(13) of the Companies Act, 2013, premium paid by the company for insurance protecting its managing director, whole-time director, manager, CEO, CFO or company secretary against liability for negligence, default, misfeasance, breach of duty or breach of trust is not treated as remuneration. However, if the person is proved guilty, the premium is treated as part of their remuneration.
Can an individual director buy cover separately?
Possibly, but a director should not assume so. In particular, a director usually cannot simply buy a copy of the company’s D&O policy. This is because that policy is built around the company as policyholder, and it is underwritten on the company’s information.
Some insurers may offer products for individual or independent directors. However, availability, structure and wording vary, and such products are not standard in every market. Therefore, an individual director considering personal cover should ask a broker what is available and how it would interact with the company’s policy.
How Side A matters to directors
Side A is the part of a company D&O policy most directly aimed at individuals. It pays for insured persons when the company does not indemnify them – for example, if the company is insolvent or legally unable to indemnify. For independent directors in particular, the adequacy of Side A cover can be a key question. See how the claim process works for Side A cover.
What a director should check before relying on the company’s policy
- Is the director within the definition of “insured person”?
- Is Side A included, and how much of the limit is available to individuals?
- Is the limit shared with the company and other directors?
- Does cover continue after the director leaves the board?
- Are outside directorships covered, if relevant?
- When does the policy expire, and will it be renewed?
What Should You Compare Before Buying D&O Insurance?
| What to Compare Before Buying D&O Insurance | Why It Matters |
|---|---|
| Policy limit | Caps what the policy will pay for all claims |
| Retention | Sets how much the company bears per claim |
| Side A coverage | Protects individuals when the company cannot indemnify them |
| Side B coverage | Reimburses the company when it indemnifies directors |
| Side C coverage | Decides whether the company itself is covered |
| Defence costs | Often the largest part of a claim; therefore, timing and effect on limit matter |
| Exclusions | Remove cover for specific situations, such as known claims |
| Extensions | Add cover for particular risks, although often with sublimits |
| Territorial scope | Decides where claims can be brought and still be covered |
| Claims-made provisions | Decide which policy responds to a claim |
| Insured persons | Decides who is protected |
| Premium | The cost of the cover |
| Taxes/charges | Add to the total payable |
| Policy wording | Governs every claim, so read it in full |
| Claims notification requirements | Late notice, for example, can affect cover |
| Renewal terms | Affect continuity of cover, especially for claims-made policies |
Common Mistakes When Buying D&O Insurance
- Choosing only on premium. In fact, a cheaper quote may simply buy less cover.
- Comparing unlike limits. In short, quotes with different limits cannot be compared on price.
- Ignoring exclusions. Indeed, one broad exclusion can remove cover for your most likely claim.
- Ignoring retention. After all, a high retention shifts cost back to the company.
- Not checking the Side A/B/C structure. As a result, individuals and the company may not be protected as expected.
- Failing to disclose relevant information. Indeed, non-disclosure can put cover at risk.
- Not reviewing claims-made requirements. As a result, gaps in continuity or late notice can affect claims.
- Not checking defence-cost provisions. For example, reimbursement-only terms can create cash-flow problems.
- Assuming every director has identical protection. However, definitions, shared limits and outside roles matter.
- Not reading the definitions. After all, they control how every other clause works.
- Not checking extensions. Consequently, needed coverages may be missing or sublimited.
- Waiting for a dispute to understand the policy. By then, it is too late to change it.
- Treating an online purchase as a substitute for understanding coverage. In short, the convenience of buying online doesn’t change the need to read the wording.
D&O Insurance Buying Checklist
| Stage | Checklist Item | Done |
|---|---|---|
| Assess | Understand the company’s D&O risk | ☐ |
| Assess | Identify directors and officers who need cover | ☐ |
| Assess | Review company structure, subsidiaries and overseas activity | ☐ |
| Prepare | Gather underwriting information | ☐ |
| Prepare | List previous and pending claims, and known circumstances | ☐ |
| Decide | Decide the desired policy limit | ☐ |
| Decide | Decide the retention | ☐ |
| Compare | Compare Side A/B/C cover | ☐ |
| Compare | Review defence-cost provisions | ☐ |
| Compare | Review exclusions | ☐ |
| Compare | Review extensions and sublimits | ☐ |
| Compare | Compare territorial and jurisdiction terms | ☐ |
| Compare | Compare insurer and policy wording | ☐ |
| Compare | Compare premiums | ☐ |
| Compare | Check taxes and charges | ☐ |
| Compare | Confirm quotes are like-for-like | ☐ |
| Buy | Review the proposal before signing | ☐ |
| Buy | Confirm policy inception date | ☐ |
| After | Confirm policy documents received and correct | ☐ |
| After | Understand the claims notification procedure | ☐ |
| After | Record the renewal date | ☐ |
Illustrative Example: Buying a D&O Policy
Illustrative example – no real insurer, price or coverage outcome is implied.
A privately held manufacturing company has five directors, including one nominee director from an investor. In addition, its shareholders’ agreement requires D&O cover. As a result, the company buys its first policy.
- Assess risk. First, the CFO lists the company’s exposures: investor relations, a large workforce, and borrowings.
- Gather information. Then the company collects its latest audited financials, board details, shareholding pattern, and a note confirming no past claims.
- Decide cover. After that, the board agrees on a limit it considers proportionate to its exposure. In addition, it asks for Side A, B, and C, and for entity EPLI because of the workforce.
- Request quotes. Then, through a broker, the company requests quotations from several insurers on the same basis.
- Compare policies. Two quotes are close on price. However, one excludes entity EPLI and has a higher retention.
- Review exclusions. Following this, the legal team checks the wording and finds a broader prior-litigation exclusion in one quote.
- Complete underwriting. Afterwards, the company signs the proposal and answers an insurer query about a supplier dispute.
- Select a policy. Eventually, the board chooses the quote that matches its required cover, not simply the cheaper one.
- Pay the premium. The company pays before the planned start date.
- Receive the policy. Finally, the CFO checks the schedule, circulates a summary to directors, and records the renewal date.
D&O Insurance Comparison Table
A standalone worksheet for comparing quotations. Complete one column per quote.
| Feature | Quote A | Quote B | Quote C | What to Compare |
|---|---|---|---|---|
| Insurer | D&O experience and claims service | |||
| Policy limit | Same limit? Any per-claim limit? | |||
| Retention | Amount and clauses it applies to | |||
| Side A | Included; any additional Side A limit | |||
| Side B | Retention and conditions | |||
| Side C | Scope of entity cover | |||
| Insured persons | Definition; former and outside directors | |||
| Defence costs | Advanced or reimbursed; inside or outside limit | |||
| Key exclusions | Differences between quotes | |||
| Extensions and sublimits | What is included and at what limit | |||
| Territory/jurisdiction | Where claims are covered | |||
| Retroactive / prior-litigation date | Continuity with previous cover | |||
| Premium | Base premium | |||
| Taxes/charges | GST | |||
| Total payable | Base premium plus GST and charges | |||
| Policy wording received | Full wording, rather than just the quote |
D&O Insurance Buying Checklist
A standalone version for internal sign-off.
| # | Item | Owner | Done |
|---|---|---|---|
| 1 | Company’s D&O risk assessed | ☐ | |
| 2 | Directors and officers requiring cover identified | ☐ | |
| 3 | Company structure reviewed | ☐ | |
| 4 | Underwriting information gathered | ☐ | |
| 5 | Previous and pending claims and circumstances listed | ☐ | |
| 6 | Desired policy limit decided | ☐ | |
| 7 | Retention reviewed | ☐ | |
| 8 | Side A/B/C cover compared | ☐ | |
| 9 | Defence-cost provisions reviewed | ☐ | |
| 10 | Exclusions reviewed | ☐ | |
| 11 | Extensions reviewed | ☐ | |
| 12 | Territorial/jurisdiction terms compared | ☐ | |
| 13 | Insurer and policy wording compared | ☐ | |
| 14 | Premiums compared | ☐ | |
| 15 | Taxes/charges checked | ☐ | |
| 16 | Quotes confirmed like-for-like | ☐ | |
| 17 | Proposal reviewed before signing | ☐ | |
| 18 | Policy inception confirmed | ☐ | |
| 19 | Policy documents received and checked | ☐ | |
| 20 | Claims notification procedure understood | ☐ | |
| 21 | Renewal date recorded | ☐ |
Conclusion
Buying a D&O policy is a structured process. First, understand the company’s exposure and who needs cover. After that, give insurers accurate information, compare quotations like-for-like, and read the wording before you commit. Then pay, check the documents, and keep the policy under review.
Since directors are usually protected as insured persons under a policy the company buys, the company’s choices directly affect their protection.
To start comparing quotations, visit SecureNow’s Directors & Officers Liability Insurance page. Later, if a claim arises, read how to file a D&O insurance claim.
This article is general information. Therefore, coverage depends on the specific policy wording. Insurance is the subject matter of solicitation.
Frequently Asked Questions
Q) How do I buy a D&O insurance policy?
A) Assess the company’s exposure, decide who needs cover, and gather underwriting information. Decide the limit, retention, and extensions, then obtain quotations through a broker, insurer or online platform. Finally, compare quotes like-for-like, complete the proposal accurately, select the policy, pay the premium, and review the documents.
Q) What information is required to buy D&O insurance?
A) Insurers commonly ask for company details, the nature of the business, revenue and financial information, board and ownership details, locations and subsidiaries, listing status, claims history and pending matters, existing insurance, and the limit and retention sought. However, requests vary by insurer.
Q) Can D&O insurance be bought online?
A) Yes, the process can start online where a platform offers it. First, you provide company details and receive quotations to compare. Insurers may still need underwriting information and a signed proposal before issuing the policy.
Q) How to buy a D&O insurance policy online from SecureNow?
A) At the time of writing, the quote form on SecureNow’s D&O page asks for contact details and the company’s industry, then shows quotations to compare. After that, the company selects cover, completes the insurer’s proposal, pays the premium, and receives the policy. However, steps may vary by insurer.
Q) Can directors buy a D&O policy for themselves?
A) Usually the company buys the policy, and directors are insured persons under it. However, a director cannot normally buy a copy of the company’s policy independently. Some insurers may offer individual-director products, but availability and terms vary.
Q) What is the Buying Process of D&O Insurance?
A) Assess the requirement, identify insured persons, gather information, decide cover and limit, obtain quotes, compare them, review the wording, complete underwriting, select the policy, pay the premium and finally review the policy after purchase.
Q) How should I compare D&O insurance quotes?
A) Align the limit and retention first. Then compare Side A/B/C cover, defence-cost terms, exclusions, extensions, territory, the policy wording, and the premium including taxes. Finally, only compare prices once the cover is comparable.
Q) What should I check before buying a D&O policy?
A) Check who is an insured person, the insuring clauses, definitions, exclusions, retention, defence-cost provisions, claims-made and notice terms, the retroactive date, prior-litigation provisions, territory, extensions and sublimits.
Q) Does the cheapest D&O policy provide adequate coverage?
A) Not necessarily. For example, a lower premium may reflect a lower limit, higher retention, narrower cover or more exclusions. Compare quotes like-for-like before deciding.
Q) What documents may be required for D&O insurance?
A) Commonly, a signed proposal form. In addition, depending on the insurer, it may also ask for recent financial statements, board and shareholding details, and information on claims or regulatory matters. However, the exact list varies by insurer and risk.
Q) How are D&O insurance premiums paid?
A) Usually in full before cover starts, by bank transfer or other methods the insurer accepts. In addition, GST applies. Cover generally begins only once the premium is received, in line with Section 64VB of the Insurance Act, 1938.
Q) What should I check after buying a D&O policy?
A) Check the schedule, wording and endorsements, insured persons, limits, retention, exclusions and extensions. Also note the claims notification process and contacts, and record the renewal date. Finally, tell the insurer about significant business changes where the policy requires it.